Building Materials/Construction
Kian Capital Builds Door and Hardware Distribution Platform with Allen Supply, TAP
October 22, 2026
Building Materials/Construction
It’s the second-largest purchase price we’ve ever seen in the market behind Home Depot’s $18 billion SRS deal and caps a remarkable 12-month span of aggressive growth for QXO.
QXO is making its boldest move yet in building materials distribution, announcing April 19 that it has reached an agreement to acquire insulation distributor and installer TopBuild for $17 billion — one of the largest transactions the durable goods distribution landscape has ever seen.
Our 2026 SHIFT Conference is coming May 12-14. Join us in Denver!
Unanimously approved by both companies’ boards and expected to close during 3Q26, the deal values TopBuild at roughly 14.9x expected 2025 EBITDA pre-synergies and 11.8x post-synergies, with about $300 million in expected cost and revenue synergies.
In comparison, that premium paid by QXO is notably less than the ~17x paid by The Home Depot for SRS. The transaction values TopBuild at $505 per share, whereas TopBuild’s stock traded as high as $550 in mid-February.
The acquisition is expected to be immediately and substantially accretive to earnings and materially expand QXO’s margins, according to the company.
“Over the past 11 months, we’ve built QXO into a market leader through more than $13 billion of acquisitions, closing on Beacon in 2025 and Kodiak earlier this month,” said QXO CEO Brad Jacobs, who stepped down from his Chairman roles at 3PL companies XPO and GXO at the end of 2025 to focus on QXO. “The TopBuild transaction will also give us critical mass in the insulation sector and expand our exposure to large, complex projects like data centers, where scale matters.”
With the addition of TopBuild — alongside its recent acquisitions of Beacon (for $11B in mid-2025) and Kodiak Building Partners (for $2.25B in February) — QXO will emerge as the second-largest publicly traded building products distributor in North America, with more than $18 billion in combined revenue and over $2 billion in adjusted EBITDA.
That trajectory is striking given QXO only launched in mid-2024 and went public in January 2025. In less than a year, the company has gone from zero revenue and EBITDA in the sector to a scaled, multi-category platform with leadership positions across key segments.
QXO said that, once the TopBuild deal is complete, it will hold:
The TopBuild acquisition alone expands QXO’s addressable market to more than $300 billion and significantly increases its exposure to large, complex commercial and industrial projects — including high-growth areas like data centers.
The combined company is expected to operate roughly 1,150 branches with about 28,000 employees and a fleet size of more than 10,000 vehicles.
“TopBuild has a deep bench of best-in-class operators, reflected in its industry-leading adjusted EBITDA margin of approximately 18%,” Jacobs continued. “We plan to replicate their best practices across QXO, including deploying their ‘special OPS’ teams to continuously improve operational excellence and customer service.”
TopBuild brings a differentiated model that blends distribution with installation services — a combination that has driven both growth and margin resilience.
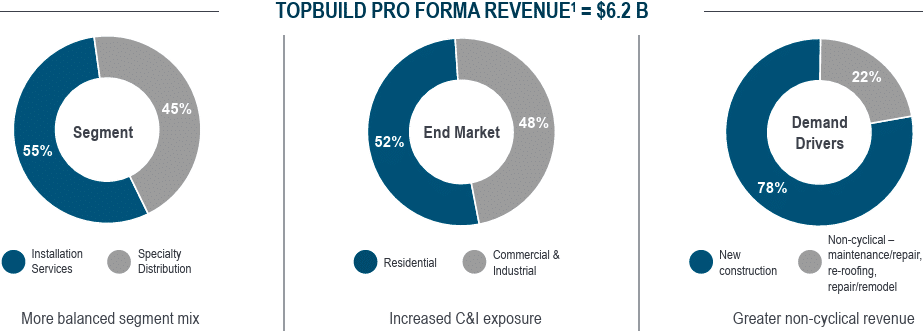
TopBuild’s distribution and installation segment mix creates a balanced exposure between residential (52%) and commercial (48%) end markets, with about 52% tied to commercial and industrial activity and 22% of revenue considered non-cyclical (repair/remodel and maintenance).
Despite ongoing softness in residential construction, TopBuild has maintained strong profitability — with adjusted EBITDA margins near 18% in 4Q25 — supported by growth in commercial and industrial demand and disciplined execution.
“We’re excited to join QXO and combine our leadership in insulation installation and specialty distribution with QXO’s scale, technology, and procurement capabilities,” Buck said for TopBuild. “Together, we’ll enhance customer service, unlock meaningful cross-selling opportunities, and drive continued growth and operating efficiency. I’m proud of our team’s track record, including a 10-year sales CAGR of 13% and adjusted EPS CAGR of 31%. Thank you to the entire TopBuild team for delivering these exceptional results.”
Any of QXO’s three deals so far would be considered a landmark transaction in building materials distribution, and QXO’s aggressive pace and scaling is historically unheard of in practically any durable goods sector — even though the company has repeatedly stated an ambitious goal of becoming a $50 billion by the middle of the 2030s.
It also validates comments made earlier this year by QXO leadership that the company was pursuing a pipeline of both mid-sized and “transformational” deals.
This one clearly falls into the latter category.
The scale of the transaction places it among the largest ever in building materials distribution — second only to Home Depot’s $18.25 billion acquisition of SRS Distribution in 2024 — and signals continued acceleration in market consolidation amongst its biggest players.
For QXO, the strategy is explicit: use scale, cross-selling opportunities and operational leverage to build toward its long-term target of $50 billion in revenue and $7.5 billion in EBITDA.
With TopBuild, that path just got significantly shorter — and far more visible.
Stay Informed
News, trends, and analysis for wholesale distribution leaders. Free, everyday.
Subscribe to MDM Update