Facilities Maintenance (MRO)
Global Industrial’s 3Q Sales Rise 10.2%, Tariff Refunds Lift Profits
November 3, 2026
MRO
Double-digit volume growth powered another strong quarter for Grainger, which raised its annual sales forecast after its best organic sales growth in nearly 4 years. Get the key metrics and our analysis.
MRO supplies distributor Grainger reported another quarter of double-digit sales growth Nov. 4 and raised its full-year outlook as industrial demand continued to improve.
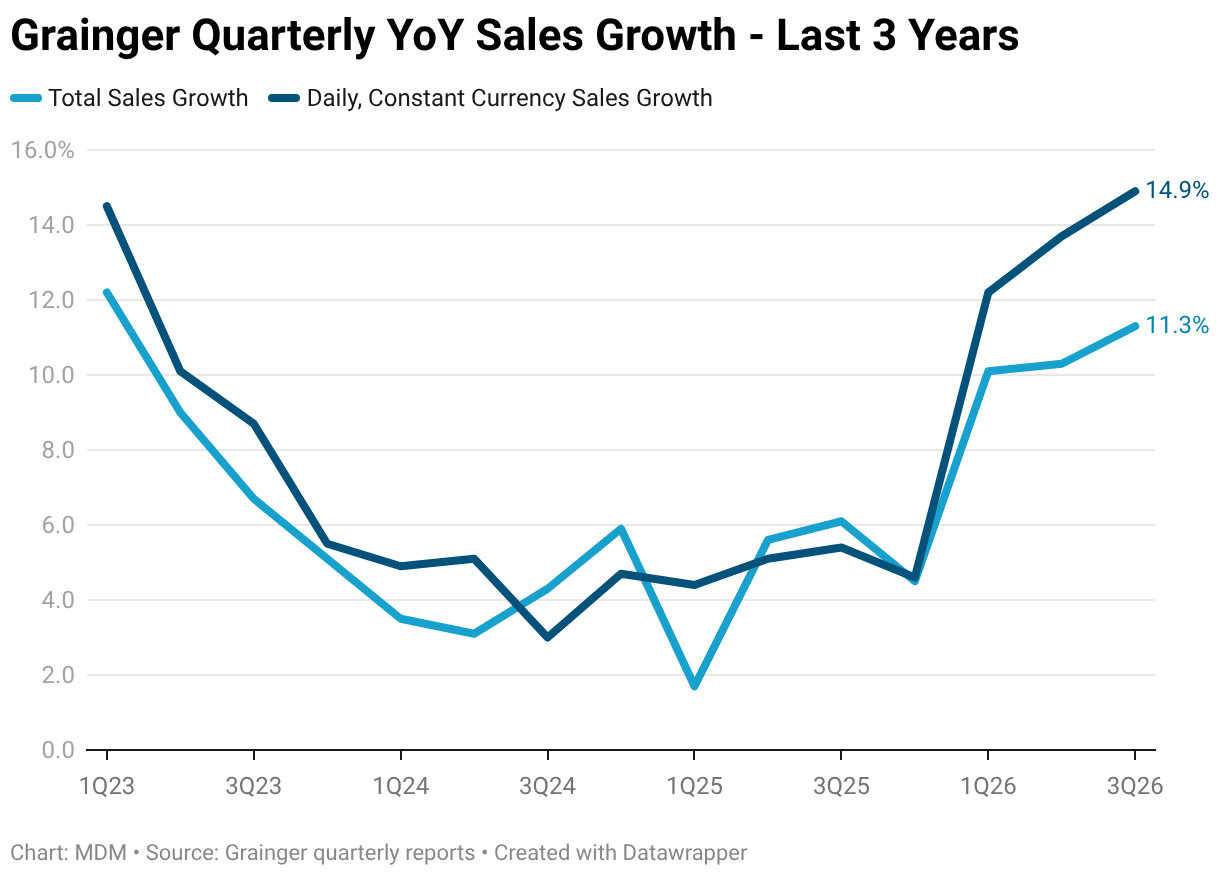
The company posted 3Q26 sales of $5.18 billion, up 11.3% year-over-year and 3.2% from 2Q. Daily organic constant-currency sales increased 14.9%, accelerating from 13.7% growth in 2Q after adjusting for currency movements and Grainger’s U.K. market exit.
Gross profit increased 11.8% year-over-year and 1.4% sequentially to $2.01 billion. Gross margin reached 38.8%, up 20 basis points from a year earlier but down 70 bps from 2Q. The sequential comparison includes a second quarter that benefited from $43 million in IEEPA tariff refunds. Grainger did not identify a new tariff-refund benefit in its 3Q materials.
See MDM’s Grainger Case Study Report – published September
MDM Podcast: Inside Our Grainger Case Study
Reported operating profit increased 62.0% year-over-year and 2.6% sequentially to $828 million. Operating margin was 16.0%, up 500 bps year-over-year but down 10 bps sequentially. Net profit attributable to Grainger increased 99.7% year-over-year and 3.0% sequentially to $587 million.
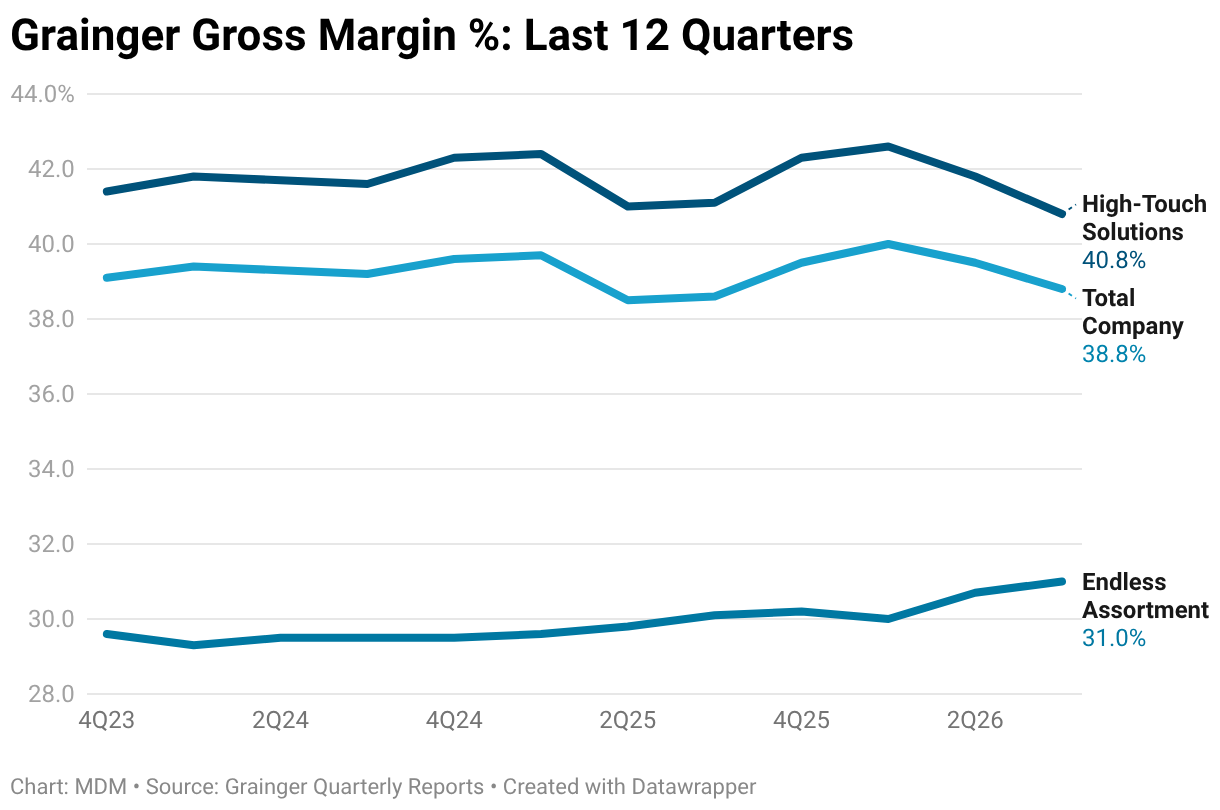
Those year-over-year profit comparisons benefited from a $196 million U.K. exit loss recorded in 3Q25 with Grainger’s divestment of Cromwell and Zoro U.K. Excluding that loss and $8 million in acquisition transaction costs this quarter, adjusted operating profit increased 18.2% year-over-year and 3.6% sequentially to $836 million. Adjusted operating margin was 16.1%, up 90 bps year-over-year and unchanged sequentially.
Grainger’s 3Q26 segment results included:
Grainger’s U.S. High-Touch business grew daily sales across every major customer end market, including mid-teens growth in manufacturing, mid-20s growth among contractors and high-teens growth in transportation.
The company implemented U.S. High-Touch price increases in September to address product inflation, freight costs and tariff changes, including higher costs for petrochemical-based safety products such as nitrile gloves. High-Touch price/cost was roughly neutral during 3Q, though freight remained a margin headwind.
Grainger now expects 2026 sales of $19.8-$20.0 billion, up from $19.4-$19.7 billion previously. That represents reported growth of 10.1-11.6% and daily organic constant-currency growth of 13.0-14.5%.
The company also raised the lower ends of its gross margin and adjusted operating margin forecasts to 39.4-39.6% and 16.0-16.2%, respectively.
The quarter included Grainger’s $210 million cash acquisition of technology, intellectual property and talent assets from Adroit Worldwide Media, announced Aug. 26. The assets will enhance High-Touch inventory management capabilities, with no material contribution to near-term financial results expected.
Grainger’s results provide another encouraging signal for broader North American industrial demand, with volume leading High-Touch growth and gains spanning every major customer market. Its performance also reflects company-specific strengths in service, digital commerce and inventory management, making its growth rate an ambitious benchmark for peers. The margin picture deserves equal attention: roughly neutral price/cost did not prevent freight from eroding High-Touch gross margin.
For other industrial distributors, healthier demand creates opportunity, but capturing profitable growth still depends on recovering delivery costs and helping customers operate more efficiently. Grainger’s AWM acquisition investment reinforces that competitive direction.
Stay Informed
News, trends, and analysis for wholesale distribution leaders. Free, everyday.
Subscribe to MDM Update