MRO
MSC’s 4Q Sales Top Outlook as Volume Gains Momentum
MSC ended its fiscal 2026 with record quarterly and annual sales sales as pricing remained strong, volumes improved and cost reductions helped margin outperform company guidance. Get the key metrics and our analysis here.
Metalworking and MRO supplies distributor MSC Industrial Supply closed its fiscal 2026 with better-than-expected fourth-quarter sales and profitability, aided by strong pricing, positive volume growth and operating expense savings.
The quarter was the first with Rob Kuhns serving as CFO after MSC appointed the former TopBuild finance chief in September.
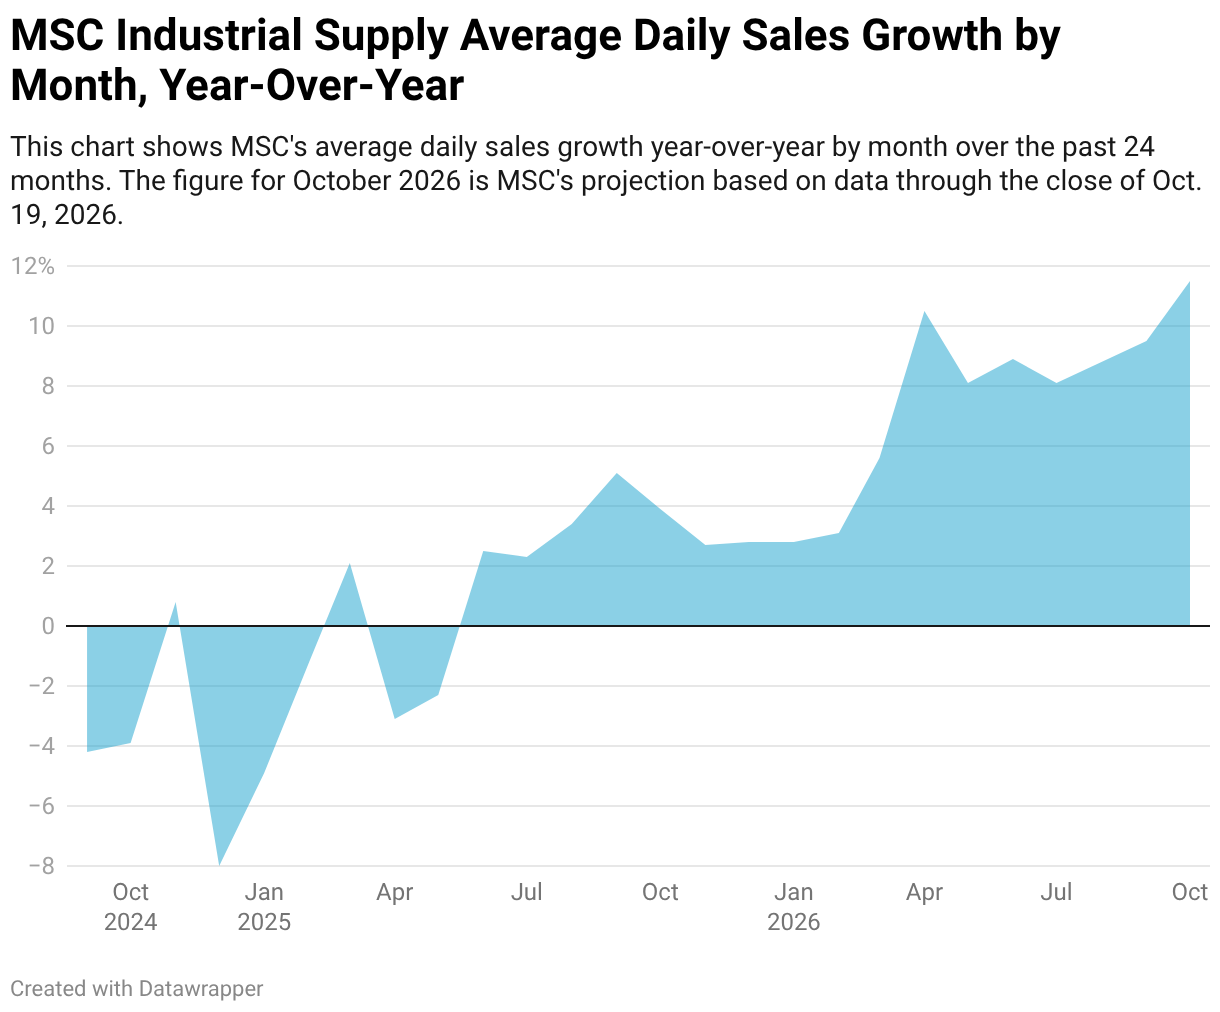
For the quarter ended Aug. 29, MSC reported record quarterly sales of $1.08 billion, up 10.3% year-over-year. Average daily sales (ADS) increased 8.6%, slightly exceeding the high end of MSC’s 6.5-8.5% guidance issued alongside its third-quarter results. By month, MSC’s ADS increased 8.9% in June, 8.1% in July and 8.8% in August for the quarter, while subsequent ADS growth were 9.5% in September. The company is projecting October 2026 ADS growth of approximately 11.5% based on sales through Oct. 19.
Pricing contributed 690 basis points to 4Q daily sales growth (down from 720 in 3Q), while volume added 160 points and foreign exchange contributed 10. Volume improved from a 50-basis-point contribution in 3Q and a 40-point decline in 2Q.
“We had a strong finish to fiscal 2026, with fourth-quarter results exceeding our expectations and sales achieving record quarterly levels,” MSC President and CEO Martina McIsaac said. “These results provide further evidence that MSC is heading in the right direction, and that the changes we have made to drive profitable growth are taking hold.”
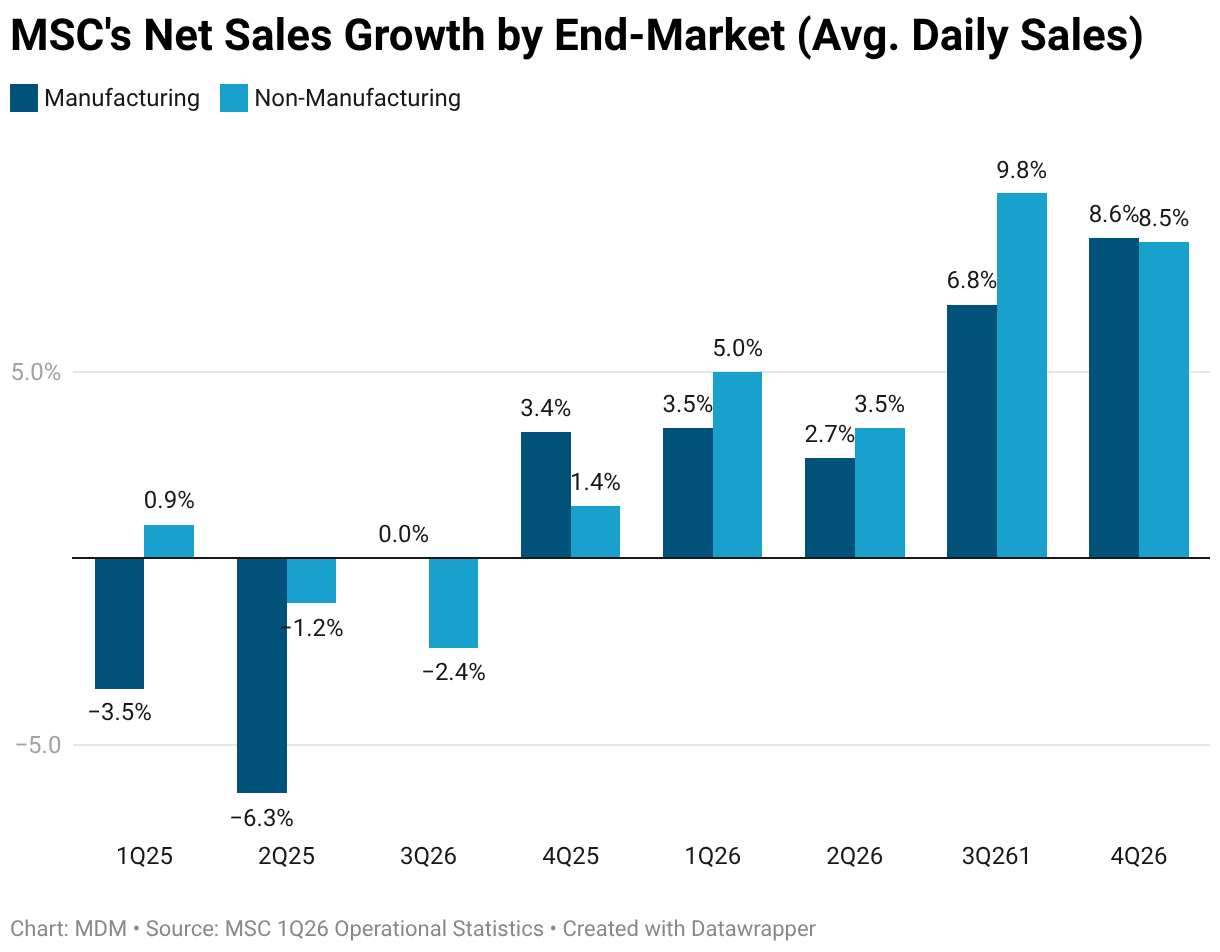
By customer type, average daily sales among core and other customers — representing 55% of company sales — increased 10.4% to underpin MSC’s healthy 3Q performance. National account sales grew 8.6%, while public sector sales decreased 1.2%. Manufacturing and non-manufacturing end-market sales increased 8.6% and 8.5%, respectively.
Gross margin improved 20 basis points year-over-year to 40.6%. Adjusted operating profit jumped 30.5% to $117.8 million, while adjusted operating margin expanded 170 basis points to 10.9%, topping MSC’s 10.0-10.8% outlook. The company generated an adjusted incremental operating margin of approximately 27%.
Reported operating profit fell 13.6% to $72.8 million, reflecting $41.8 million of asset impairment and related charges. Reported net profit attributable to MSC declined 15.2% to $47.9 million, while adjusted net profit increased 33.8% to $81.5 million.
MSC also highlighted its productivity gains. The company generated approximately 9% daily sales growth with about 250 fewer associates than a year earlier, while sales per representative per day improved by a mid-teens percentage. Total headcount ended 4Q at 7,028, down 3.5% year-over-year, while field sales headcount decreased 4.6% to 2,515.
MSC Begins New Chapter Marked by Sales Execution & Efficiency (January)
Other 4Q operating figures included:
- Sales to customers with an In-Plant program increased 19%, while vending sales grew 20%.
- MSC ended the quarter with 431 In-Plant programs, up from 411 a year earlier.
- Installed vending units increased 5.0% to 31,078.
- eCommerce sales increased 8.1% to $677.3 million and represented approximately 62.8% of total sales.
For the full fiscal year, MSC sales increased 6.4% to $4.01 billion, with average daily sales up 6.0%. Pricing contributed 620 basis points to annual daily sales growth, while volume declined 40 points.
Full-year gross margin improved 10 basis points to 40.9%. Reported operating profit increased 6.3% to $320.6 million and attributable net profit rose 11.7% to $222.6 million. Adjusted operating profit increased 20.1% to $379.3 million, with adjusted operating margin expanding 110 basis points to 9.5%.
MSC expects fiscal 1Q27 average daily sales growth of 9.5-10.5% and adjusted operating margin of 9.5-10.1%. September daily sales increased 9.5%, while preliminary October growth was approximately 11.5% through Oct. 19.
“While we remain mindful of inflationary headwinds and tougher comparisons looking ahead, we are confident that profitable growth will remain the trend. Our strategic execution is building momentum as our end markets continue to improve,” McIsaac added. “This positions MSC well entering fiscal 2027, as demonstrated by first-quarter sales trends showing low double-digit growth to date.”
MDM Analysis
Pricing still supplied most of MSC’s growth, but accelerating volume provides a healthier demand signal for metalworking and MRO distributors. Just as important, MSC converted that growth into margin expansion while operating with fewer associates — evidence that salesforce restructuring and cost actions are producing leverage.
Peers should note the combination: disciplined pricing can protect against inflation, but productivity gains determine how much topline growth reaches profit. MSC’s fiscal 4Q exit rate suggests industrial demand entered fiscal 2027 with improving momentum, especially evidenced the company’s projected October 2026 ADS growth of 11.5%.