Adhesives
H.B. Fuller Rejects Ancora’s Increased Bid for Building Adhesives Business
Ancora raised its offer to as much as $1.4 billion, but Fuller’s board again rejected it. The adhesives maker will review selected businesses for potential divestitures.
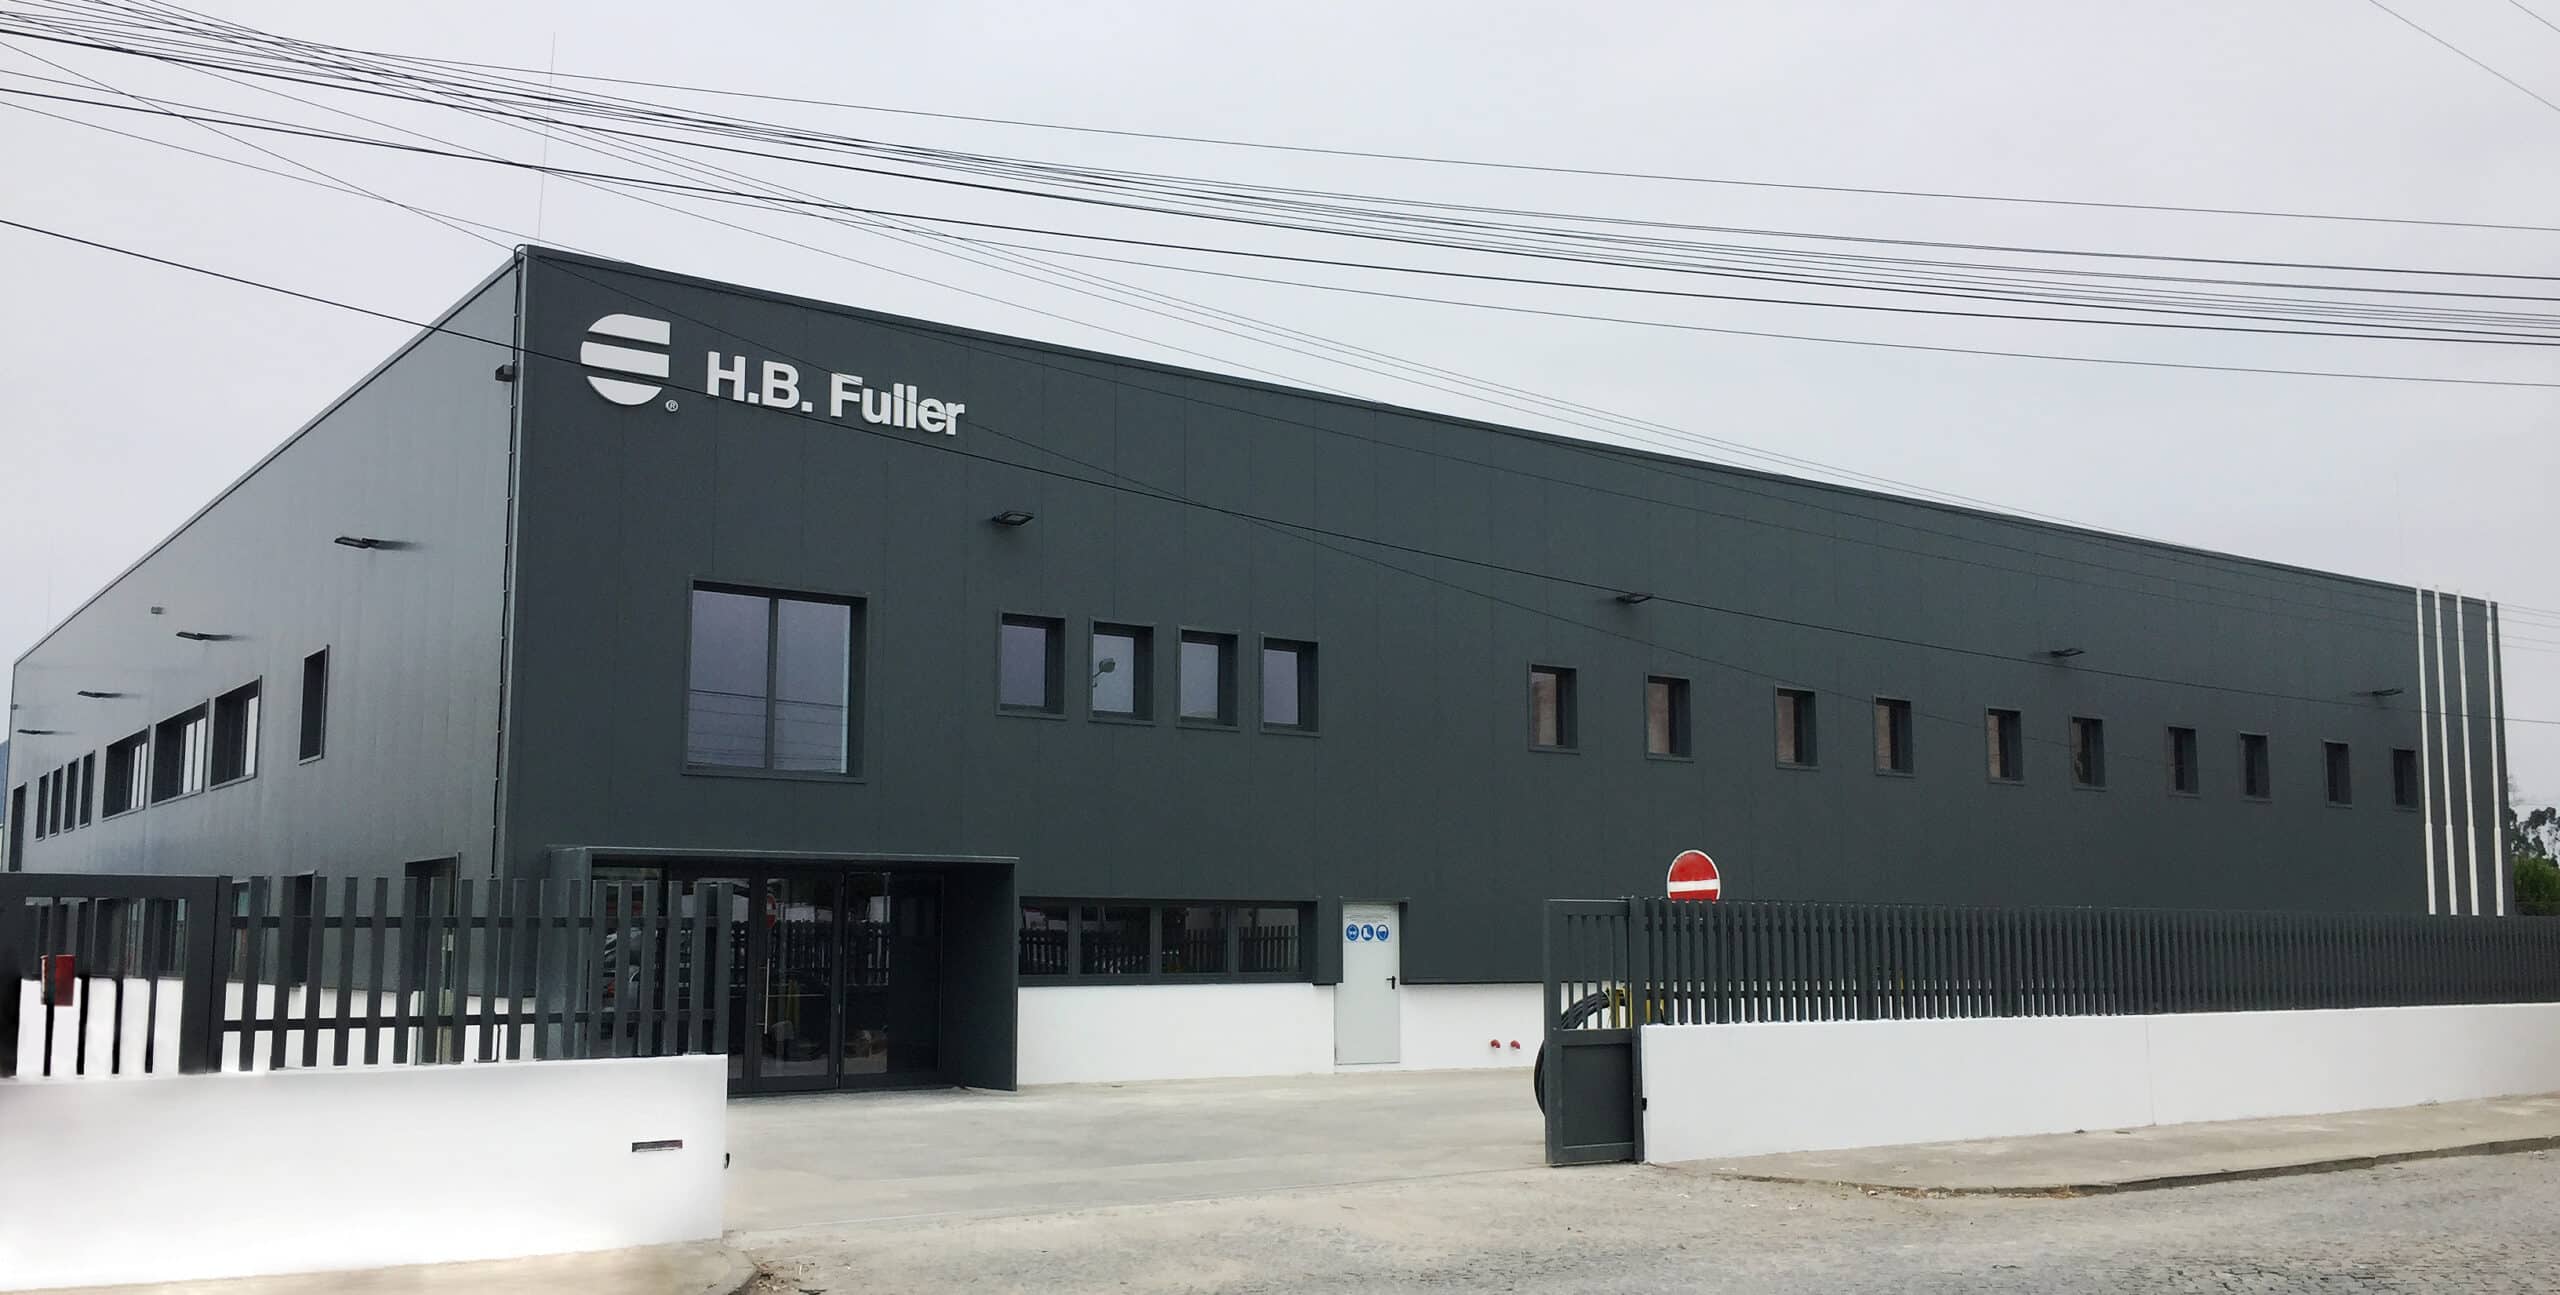
St. Paul, MN-based adhesives manufacturer H.B. Fuller announced Oct. 19 that its board unanimously rejected Ancora Holdings Group’s second unsolicited, nonbinding proposal to acquire its Building Adhesive Solutions (BAS) business for $1.2 billion-$1.4 billion in cash.
The board said the increased price inadequately reflected BAS’ organic growth momentum, role within Fuller’s broader business and potential benefits from its Project Quantum Leap restructuring initiative. The proposal also continued to lack key details, leaving its terms “highly conditional,” Fuller said.
Ancora, a Fuller shareholder, initially proposed buying BAS for $1.1 billion-$1.2 billion in cash on Aug. 12. Fuller’s board unanimously rejected that offer Aug. 24, citing valuation, financing and operational concerns.
In its first rejection, Fuller said BAS shared manufacturing operations with its other businesses at more than 30 plants worldwide. Separating the segment would create operating inefficiencies, the company argued, with taxes and lost efficiencies materially offsetting the benefits of debt reduction.
Fuller also pointed to BAS’ second-quarter performance — including 6% organic growth and a 10% EBITDA improvement — as evidence of its earnings potential.
Ancora submitted its increased offer Sept. 29, arguing that selling BAS would accelerate Fuller’s debt reduction and lower balance sheet risk. It disputed Fuller’s separation concerns, citing work with advisers and operating partners that included former Fuller management.
The investment firm also said Fortress Investment Group had provided a “highly confident” letter regarding its ability to supply the necessary debt financing. Ancora said its revised offer represented approximately half of Fuller’s equity value at the time, while BAS accounted for about 20% of consolidated revenue.
Alongside its latest rejection, Fuller announced a market review of selected businesses and product lines considered less integral to its strategy. It expects to complete that process by year-end 2026, with any sale proceeds intended for debt reduction.
The review will weigh separation costs, tax implications, lost operating efficiencies and effects on Project Quantum Leap.